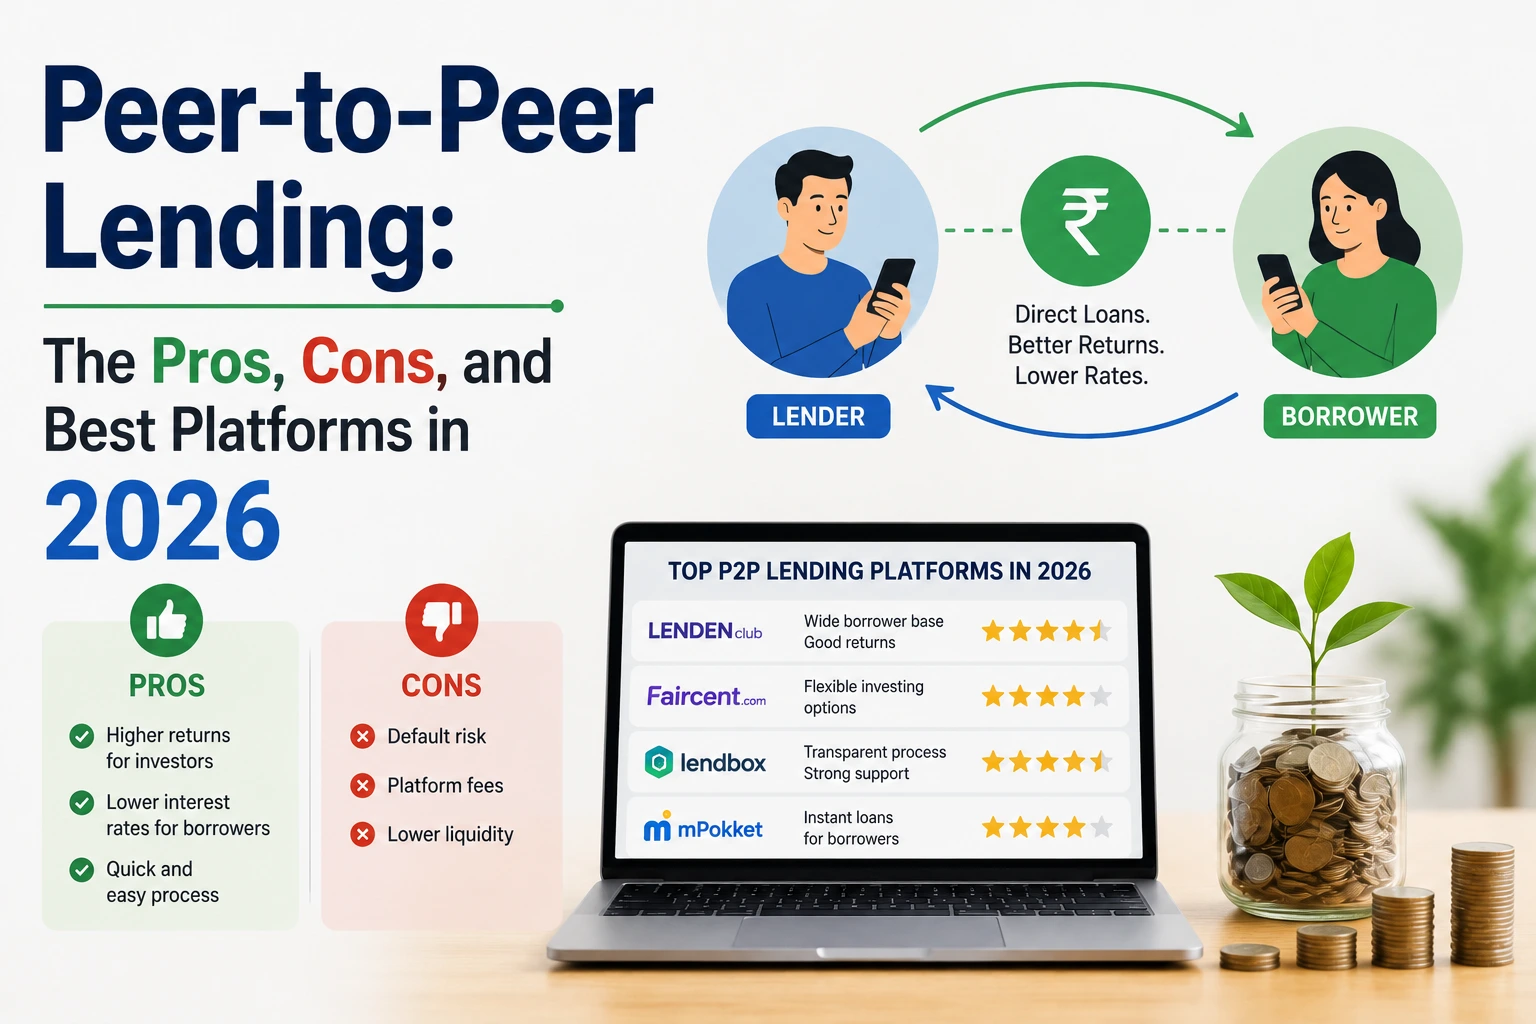
Peer-to-peer lending platforms, connecting individual investors directly with borrowers seeking personal loans outside the traditional banking system specifically, have continued offering genuinely higher potential returns than traditional savings accounts or many conventional fixed-income investments, though this higher potential return comes paired with genuinely higher risk, specific borrower default risk, platform-specific risk, and considerably reduced liquidity compared to more traditional, established investment categories, meaning P2P lending represents a genuinely distinct risk-return tradeoff investors should evaluate carefully rather than treating simply as an attractive higher-yield alternative to traditional savings without this additional risk consideration.
Evaluating peer-to-peer lending’s genuine investment merit in 2026 requires understanding this specific risk-return tradeoff honestly, the genuine borrower default risk that directly affects investor returns, the specific platform risk associated with the P2P lending company itself, and the considerably reduced liquidity compared to more traditional investment options, since these specific risk factors together determine whether P2P lending genuinely represents an appropriate investment allocation for a given investor’s specific risk tolerance and broader portfolio diversification needs.
Understanding Genuine Borrower Default Risk
P2P lending investor returns directly depend on borrowers actually repaying their loans as agreed, meaning borrower default, a borrower failing to repay all or part of their loan, directly and immediately reduces an investor’s actual realized return below whatever the loan’s stated interest rate initially suggested, a genuine risk consideration that differs meaningfully from more traditional fixed-income investments where this specific individual borrower default risk typically gets pooled and diversified across a considerably larger, more institutionally managed borrower base.
Diversifying P2P lending investment allocation across a considerably large number of individual loans, rather than concentrating investment in a small number of individual loans, meaningfully reduces the impact any single specific loan default has on an investor’s overall P2P lending portfolio return, since spreading investment across many separate loans means any individual default represents only a small fraction of the total invested amount rather than a potentially significant portion of a more concentrated investment allocation.
Platform Risk and Considerations
P2P lending platform risk, the risk that the lending platform itself experiences financial difficulty or ceases operations entirely, represents a genuinely distinct risk consideration beyond individual borrower default risk alone, since a platform’s own operational continuity affects an investor’s ability to continue receiving loan payment processing and, in some specific platform structures, could genuinely affect an investor’s ability to recover their outstanding invested principal if the platform itself experiences significant financial distress.
Evaluating a specific P2P lending platform’s own financial stability, regulatory compliance history, and loan servicing track record before committing significant investment specifically addresses this platform risk consideration, since platform quality and stability genuinely varies across the different available P2P lending platforms, making platform-specific due diligence a genuinely important evaluation step beyond simply evaluating individual loan opportunities within a given platform alone.
P2P Lending Risk Factors Summarized
Summarizing the core risk categories investors should genuinely evaluate before P2P lending investment.
| Risk Factor | What It Involves | Mitigation Approach |
| Borrower default risk | Individual loans failing to repay as agreed | Diversify across many individual loans |
| Platform risk | The lending platform itself facing financial difficulty | Evaluate platform stability before investing |
| Liquidity risk | Difficulty accessing invested funds before loan maturity | Only invest funds not needed for near-term liquidity |
| Tax complexity | Interest income and default losses require careful tracking | Maintain thorough records, consider tax software |
Liquidity Considerations
P2P lending investments typically carry considerably reduced liquidity compared to more traditional, publicly traded investment options, since an individual P2P loan investment generally cannot be easily sold or converted back to cash before the underlying loan’s own maturity date without using a specific platform’s secondary market feature, where available, which itself may carry additional transaction costs or reduced sale value compared to the loan’s original invested amount.
This liquidity limitation means P2P lending investment allocation should generally represent funds an investor genuinely does not anticipate needing access to before the underlying loans’ typical maturity timeframe, commonly three to five years for many P2P lending loan products specifically, rather than funds an investor might reasonably need for near-term liquidity needs given this asset category’s genuinely more limited liquidity compared to more traditional, readily tradeable investment options.
P2P lending platform analysts and alternative investment researchers with genuine current data can Write for us and share your own expertise with our readers.
Evaluating Whether P2P Lending Fits a Specific Portfolio
P2P lending investment generally makes most sense as a genuinely modest allocation within a broader, well-diversified investment portfolio specifically, rather than a significant or primary portfolio allocation, given this asset category’s genuinely elevated risk profile, reduced liquidity, and less established track record compared to more traditional investment categories with considerably longer performance history and broader institutional adoption.
Investors genuinely considering P2P lending investment are well served starting with a modest allocation specifically, using this initial, smaller investment to genuinely evaluate a specific platform’s actual loan performance and their own comfort with this asset category’s particular risk-return profile before potentially expanding that allocation further, rather than committing a significant portion of investment capital to this asset category without this initial, more cautious evaluation period specifically informing that larger allocation decision.