
Revolut reached 50 million customers globally in early 2026 and reported 2.2 billion US dollars in revenue for 2024. Chime, the largest US neobank by customer count, exceeded 22 million account holders. Monzo in the UK crossed profitability for the first full fiscal year in 2024. These are not fringe financial products. Neobanks have become a significant force in retail banking, and in several specific use cases, they now offer materially better products than their traditional competitors.
The question is not whether neobanks are legitimate or here to stay. That debate is settled. The question for a consumer in 2026 is whether a neobank, a traditional bank, or a combination of both best matches their specific financial behaviour, risk tolerance, and product requirements. The answer depends on factors that are more specific than most comparison articles acknowledge.
What Neobanks Actually Are
Neobanks are technology companies that deliver banking services through mobile-first applications, with no physical branch network. They typically do not hold banking licences directly in all markets, instead partnering with licensed banks to hold customer deposits (which are then protected by deposit insurance schemes like the FDIC in the US or FSCS in the UK). In some markets, including the EU under PSD2, neobanks have obtained their own banking licences: Revolut received its UK banking licence in July 2024 after a multi-year process, and Monzo holds a full UK banking licence.
The business model differs fundamentally from traditional banking. Traditional banks earn margin primarily from the spread between deposit rates paid to customers and lending rates charged to borrowers. Neobanks earn through interchange fees on card transactions, premium subscription tiers, currency exchange margins, and increasingly through lending products introduced as they scale. The difference in business model drives the difference in product design: neobanks optimise for engagement and transaction volume, which pushes them toward better UX, lower fees, and higher-visibility savings rates.
Where Neobanks Win
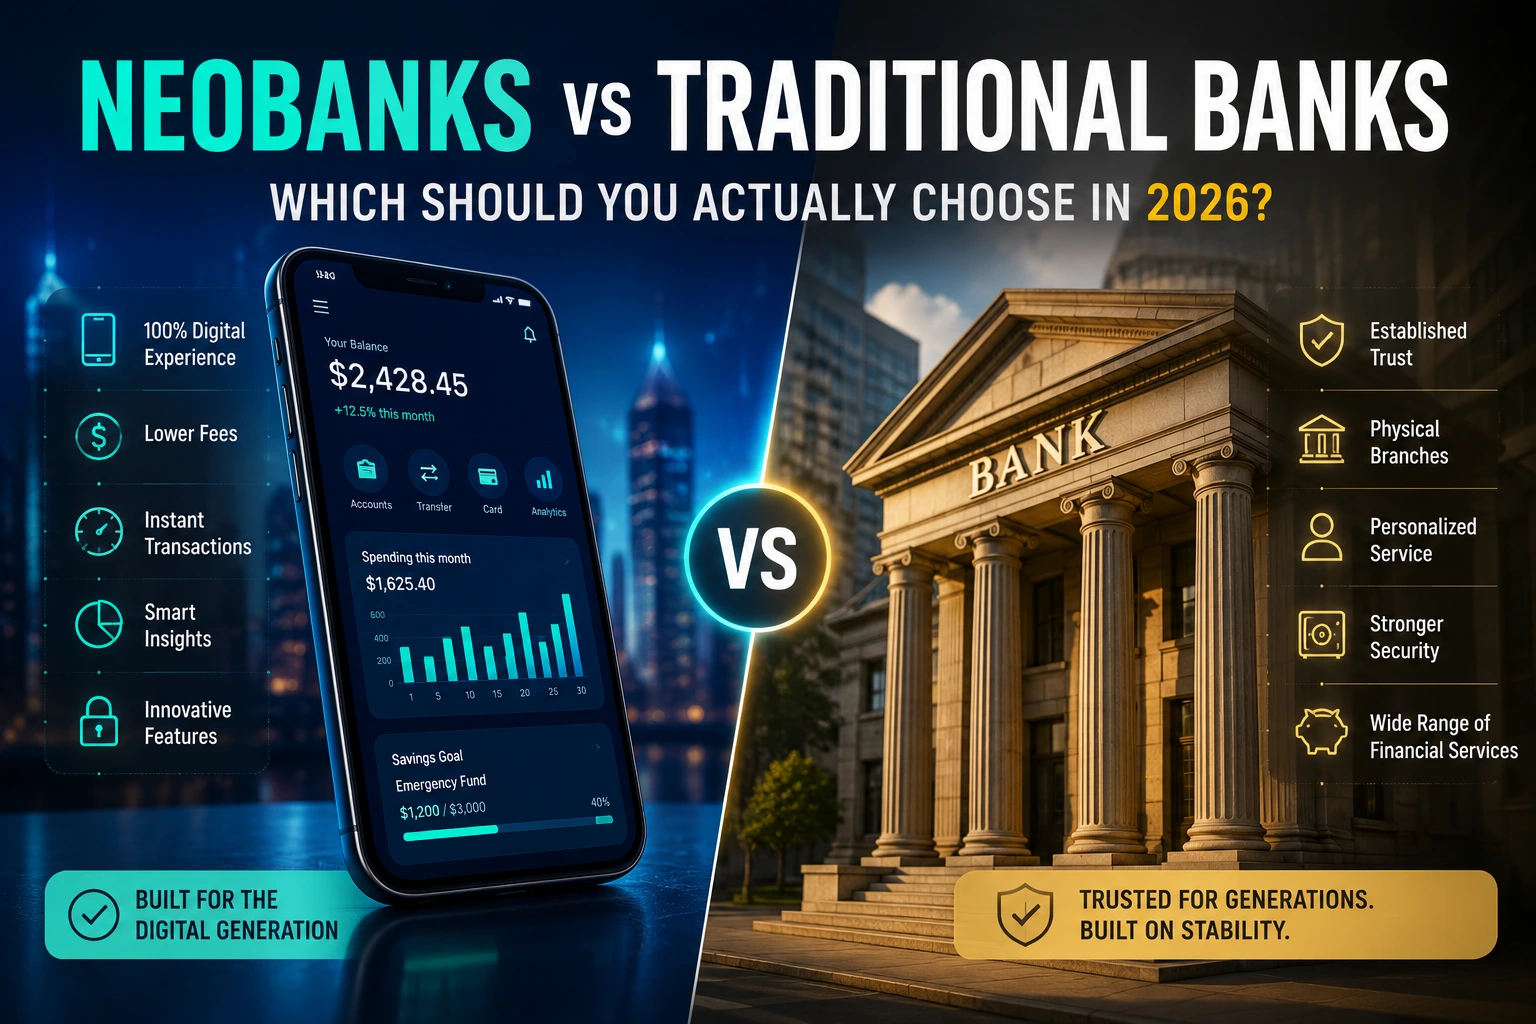
Neobanks consistently outperform traditional banks in four areas: savings rates, international transactions, user experience, and fee structures on everyday accounts.
On savings rates, neobank high-yield savings accounts in the US have consistently offered 4.5 to 5.2 percent APY in 2025 and into 2026, while the average savings account rate at the four largest traditional US banks (JPMorgan Chase, Bank of America, Wells Fargo, Citibank) remained below 0.5 percent APY for standard accounts. The gap is not trivial: on a 20,000 US dollar balance, the difference between 0.4 percent and 5.0 percent APY is approximately 920 US dollars per year in interest.
On international transactions, Revolut, Wise, and Starling Bank offer mid-market rate foreign exchange with low or zero transaction fees, compared to traditional bank foreign transaction fees of 2 to 3 percent of transaction value plus currency conversion margins. A traveller spending 3,000 US dollars abroad saves 90 to 150 US dollars in fees versus a standard bank account.
On user experience, neobank mobile applications consistently score higher in app store ratings and usability studies. Features including real-time spend notifications, instant virtual card generation, automated savings round-ups, and spending categorisation by merchant type are standard on neobank apps and often absent or poor on traditional bank mobile applications.
Where Traditional Banks Win
Traditional banks retain significant advantages in four areas: product breadth, physical access, credit relationships, and the depositor trust that comes from institutional history.
Product breadth matters for customers who need mortgages, business credit, investment accounts, insurance products, or private banking services from a single provider. Neobanks are increasingly expanding into lending (Revolut launched personal loans in the UK in 2025, Chime launched a secured credit card), but they are not yet competitive with traditional banks across the full range of financial products a household needs over a lifetime.
Physical access to branches and cash deposit facilities remains a significant limitation for neobanks. Chime’s ATM network covers 60,000 fee-free ATMs through the MoneyPass and Visa Plus Alliance networks, but cash deposits require purchasing a money order or using retail partners. For small business owners, tradespeople, or individuals who handle significant cash regularly, the absence of cash deposit infrastructure is a practical limitation.
Credit relationships at traditional banks, particularly for mortgages and business loans, benefit from the bank’s internal knowledge of a customer’s account history, income patterns, and relationship tenure. This relationship credit scoring is not available to neobank customers applying for mortgages at a different institution.
A Head-to-Head Comparison
| Feature | Neobanks (avg) | Traditional Banks (avg) | Winner |
|---|---|---|---|
| Savings APY | 4.5–5.2% | 0.1–0.5% | Neobank |
| Monthly account fees | $0 | $5–$15 (waivable) | Neobank |
| Foreign transaction fees | 0–0.5% | 2–3% | Neobank |
| Branch access | None | Widespread | Traditional |
| ATM network | 40K–60K (fee-free) | Widespread + surcharges | Tie |
| Cash deposit | Limited | Full | Traditional |
| Mortgage products | Limited | Full range | Traditional |
| Customer service | App/chat | Phone/branch | Traditional |
| FDIC/FSCS protection | Yes (via partner) | Yes | Tie |
| App quality | Excellent | Variable (often poor) | Neobank |
The FDIC and Deposit Safety Question
Deposit safety is the most commonly raised concern about neobanks, and it is a legitimate question that deserves a specific answer. US neobanks including Chime, SoFi, and Ally hold customer deposits through FDIC-insured partner banks, meaning the 250,000 US dollar per depositor per institution protection applies to customer balances. Chime’s deposits are held at Bancorp Bank and Stride Bank, both FDIC members.
The risk is not zero. The 2024 Synapse Financial Technologies bankruptcy, in which approximately 85,000 customers across multiple neobanks temporarily lost access to funds due to a dispute over reconciliation records between Synapse and its partner banks, demonstrated a real structural risk specific to the neobank-as-intermediary model. Customers of direct FDIC member banks (traditional banks or neobanks with their own banking licences) do not carry this intermediary reconciliation risk.
Which to Choose and How to Use Both
The optimal strategy for most consumers in 2026 is not choosing one or the other. It is using both in combination, with each doing what it does best. A high-yield neobank savings account captures the rate differential of 4 to 5 percent versus the traditional bank’s sub-0.5 percent. A traditional bank primary account maintains the credit relationship needed for a future mortgage and provides branch access for cash handling. A neobank travel card (Revolut or Wise) handles international spending at mid-market rates.
The combination approach requires slightly more account management but captures the material financial advantages of both without accepting the limitations of either exclusively.