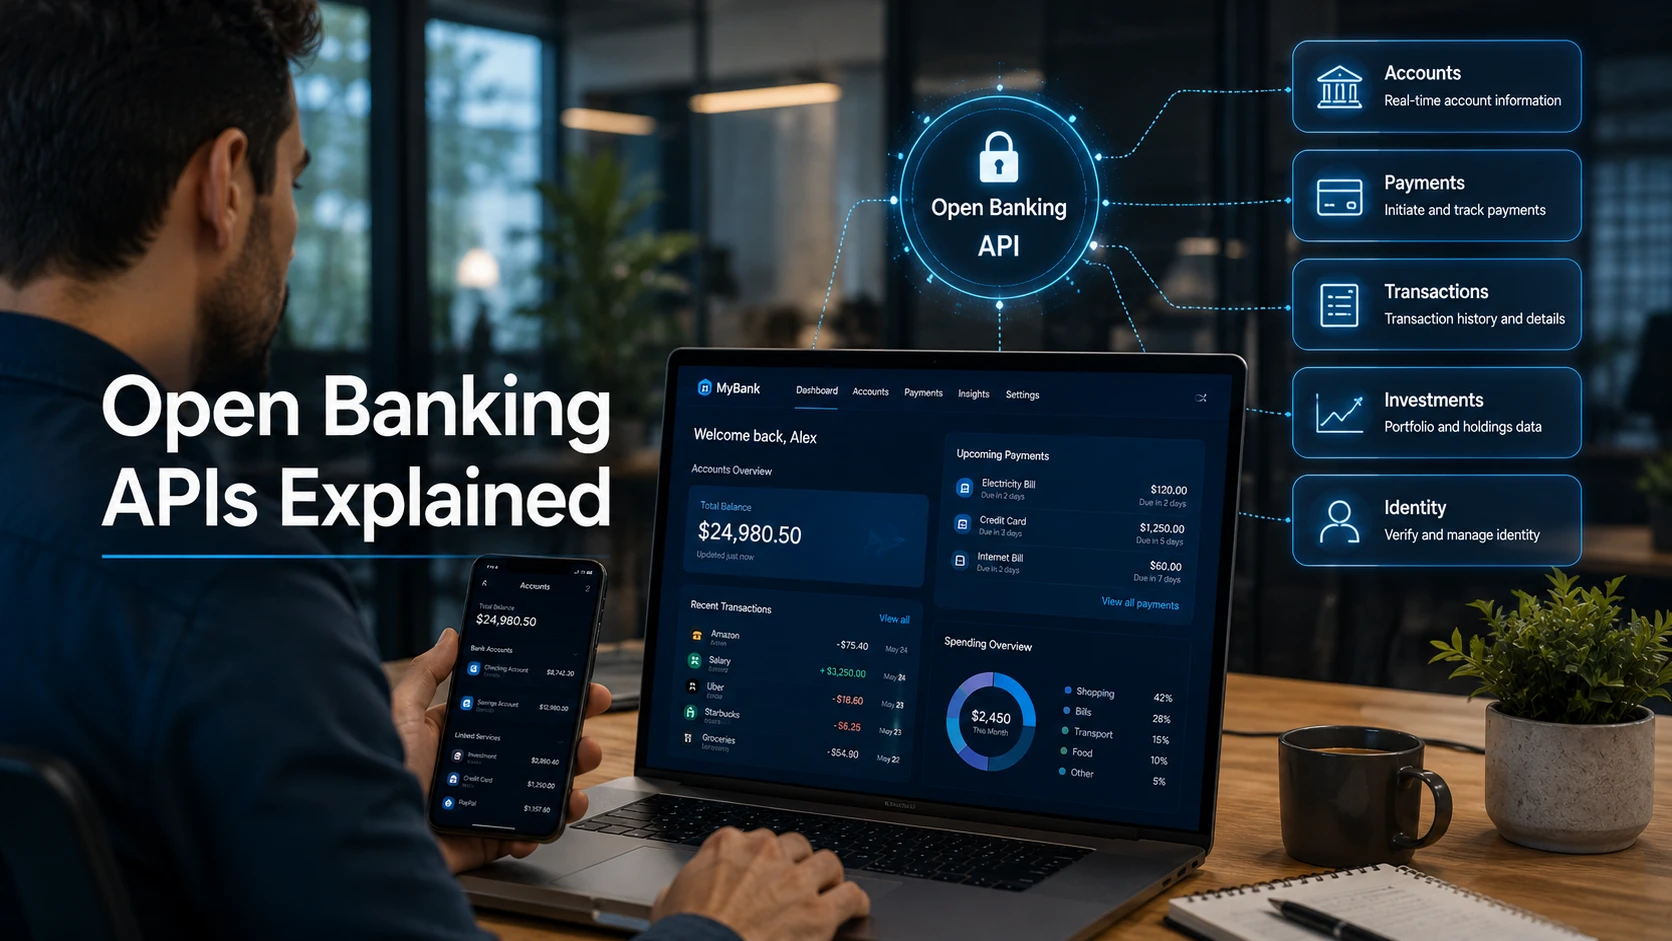
For most of banking’s history, your financial data lived in a closed box. Your bank held it. No one else could access it without a mountain of paperwork and lengthy approval processes. Open banking changes that. With your consent, your bank now shares your financial data with third-party apps through standardized connections called APIs.
What Open Banking Actually Means
Open banking is a regulatory and technical framework that requires (or encourages) banks to share customer financial data with authorized third parties through secure application programming interfaces (APIs), provided the customer gives explicit consent. The keyword is consent.
The Problem With Closed Financial Systems
Before open banking, accessing your own financial data required you to either manually download it or share your banking login credentials directly with a third-party app. That second option was widespread and deeply problematic from a security standpoint.
Open banking solves this through tokenized access. The app gets a secure token that allows read or write access to specific data categories. Your actual password never leaves the bank.
What an Open Banking API Actually Does
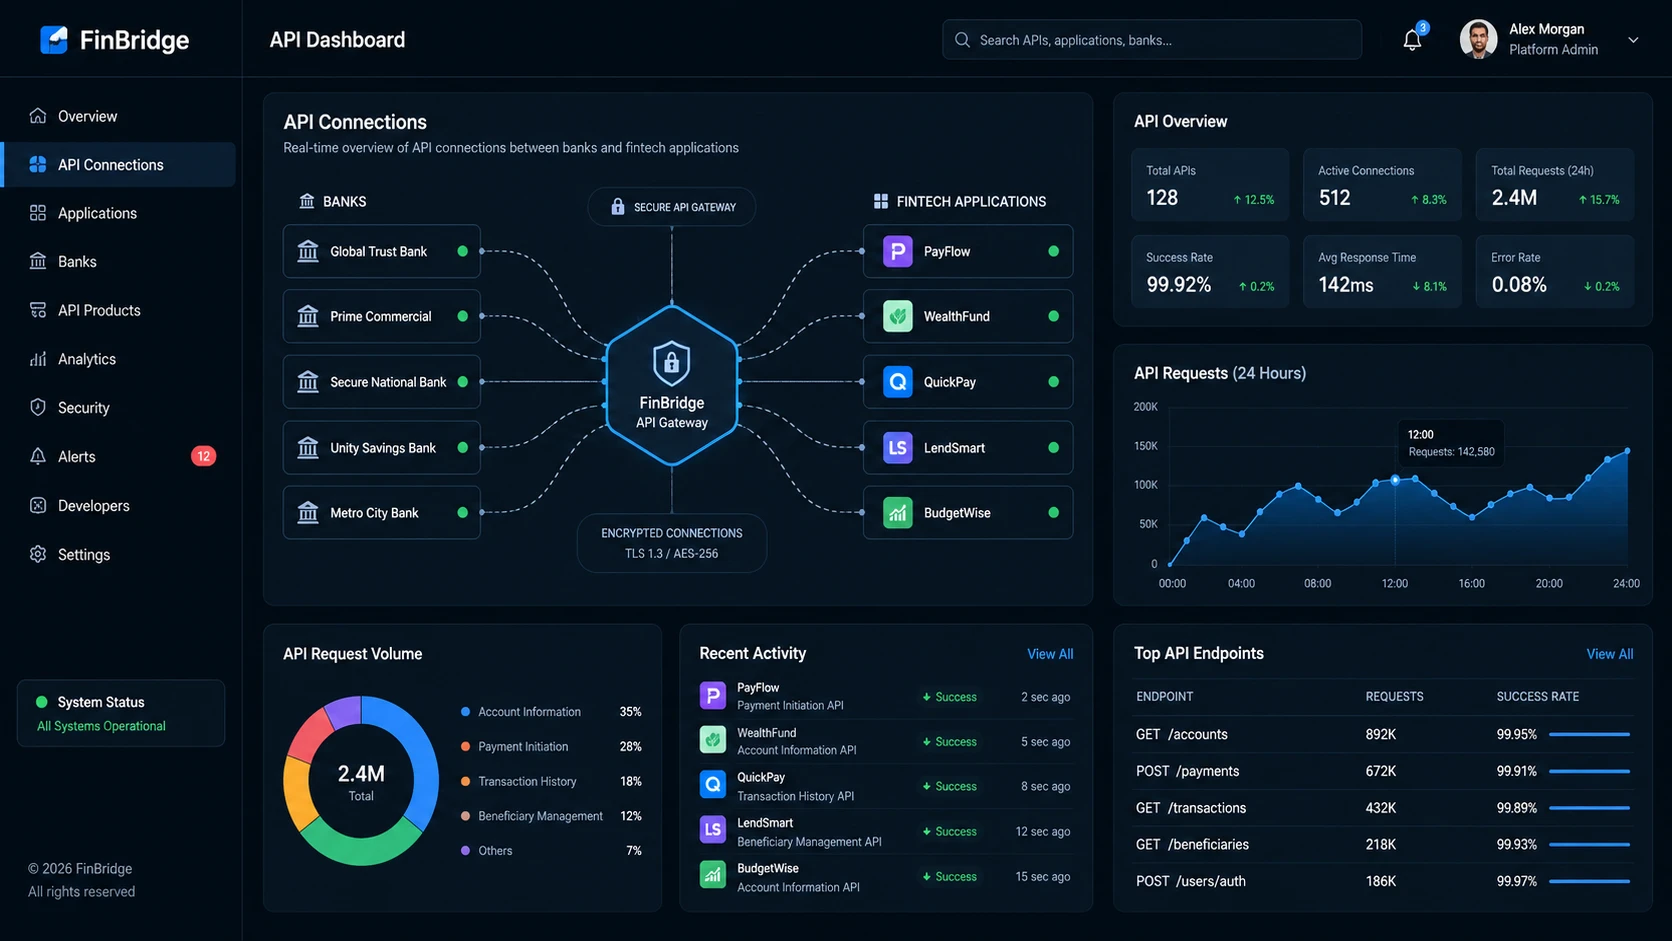
An open banking API is a standardized set of endpoints that a bank exposes so authorized apps can request specific data or initiate specific actions. Common capabilities include: reading account balances and transaction history, verifying account ownership, initiating payments directly from a bank account, and accessing loans and savings data.
How Open Banking Works in Practice
The Three Parties Involved
- Account Information Service Providers (AISPs) read your data: budgeting apps, financial planning tools, and accountancy software.
- Payment Initiation Service Providers (PISPs) can initiate payments. Direct bank transfers without card networks.
- Banks and financial institutions are the data holders. They expose the API endpoints and handle authentication.
Real-World Examples You’re Probably Already Using
Personal finance apps that categorize spending across all your accounts. Mortgage and loan applications that verify income in real time, reducing approval time from weeks to minutes. Direct bank payment options at checkout. Business accounting platforms that automatically reconcile transactions.
Open Banking Around the World in 2026
Europe’s PSD2 Framework
The EU’s Payment Services Directive 2 (PSD2), in force since 2018, mandated open banking for EU banks. By 2026, the follow-on regulation PSD3 will be implemented in multiple member states. The UK maintained and expanded its own framework independently post-Brexit.
USA, Australia, and Asia: Different Timelines, Same Direction
The CFPB’s open banking rule, finalized in late 2024, created legal clarity in the US. Australia’s Consumer Data Right covers banking, energy, and telecommunications. India’s Account Aggregator framework is one of the most ambitious implementations globally.
Open Banking for Businesses
Cash Flow Management Tools
Small and mid-sized businesses can now connect all their bank accounts, payment processors, and lending facilities into a single real-time dashboard. For a business managing payroll, vendor payments, and seasonal cash flows, this visibility is genuinely valuable.
Instant Credit Decisioning
Open banking-powered lenders access 12 to 24 months of real transaction data with applicant consent. They see actual cash flows, not just declared income. Several UK and European SME lenders now complete underwriting in under an hour using open banking data.
Is Your Data Safe With Open Banking?
Regulated open banking frameworks have strong security requirements. Third-party providers must be licensed and regulated. The tokenized access model means your banking password is not exposed. The risk depends on the quality of the individual app, not the framework itself.
- Only connect to apps explicitly licensed as open banking providers in your country.
- Review the permissions you grant, many apps request more access than they need.
- Check what data the app stores. Some aggregate histories; others query in real time and store nothing.
- Revoke access for apps you no longer use through your bank’s connected apps screen.
Expert Tips for Consumers
- Use your bank’s official portal to see which apps have access — not just the app’s own settings.
- Check whether the app requests read-only (AISP) or payment initiation (PISP) access. A budgeting app doesn’t need payment initiation.
- Read the privacy policy of financial comparison tools before connecting. Some monetize your data.
- Refresh consents annually. Many frameworks expire access after 90 to 180 days by design.
Common Misconceptions
- Banks give your data to anyone – false. Your explicit consent is always required.
- Open banking is just for mobile apps – it’s infrastructure supporting everything from embedded finance to B2B payment rails.
- If the app gets hacked, your account is accessible – a properly implemented token has limited permissions and cannot initiate payments without stronger authentication.